What is FD laddering and how does it work?
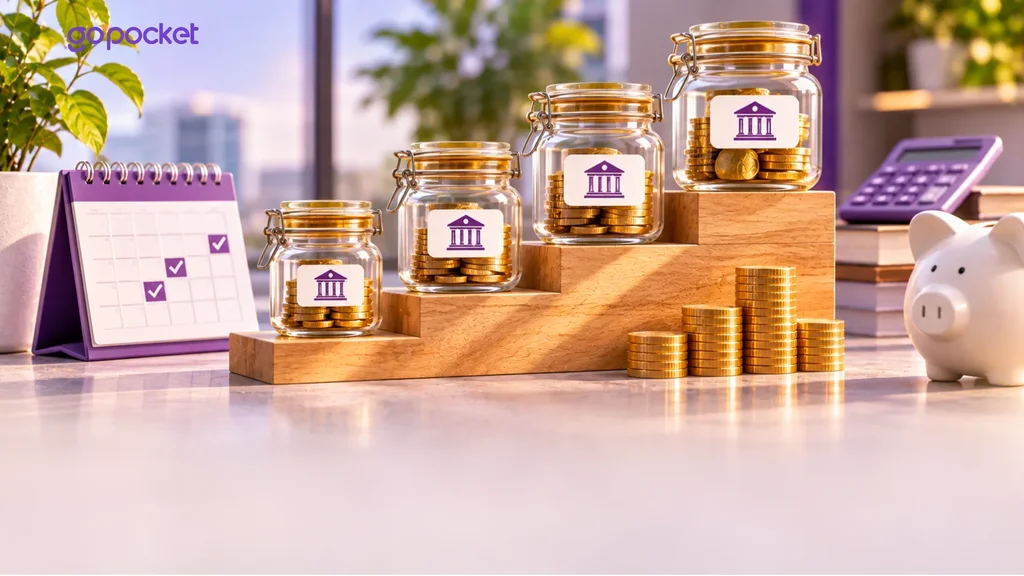
FD laddering means splitting one lump sum across several deposits of different tenures, so that a portion matures every year instead of all of it maturing on the same date. As each deposit matures, it is either used or reinvested at the prevailing rate. The method removes the need to guess where interest rates are heading, which matters in a year like 2026 when the RBI has moved from a long pause to a hike and a calibrated tightening stance.
The problem laddering solves
A saver with Rs 5 lakh and a five-year horizon faces one awkward decision: lock the whole amount now at today's rate, or wait for a better rate that may or may not arrive. Both choices are bets on the rate cycle.
Locking everything in has a second cost that is easy to miss. If money is needed before maturity, breaking a single large deposit usually means a penalty applied to the whole amount, not just the part needed.
A ladder sidesteps both problems. Part of the money is always close to maturing, and part is always locked at a longer tenure.
How to build a five-year ladder
Take Rs 5 lakh and split it into five deposits of Rs 1 lakh each, with tenures of one, two, three, four and five years.
| Deposit | Amount | Tenure | Matures in |
| 1 | Rs 1,00,000 | 1 year | Year 1 |
| 2 | Rs 1,00,000 | 2 years | Year 2 |
| 3 | Rs 1,00,000 | 3 years | Year 3 |
| 4 | Rs 1,00,000 | 4 years | Year 4 |
| 5 | Rs 1,00,000 | 5 years | Year 5 |
At the end of year one, the first deposit matures. If the money is not needed, it is reinvested for five years. The same happens in year two, and so on. From year five onwards, the ladder is self-sustaining: one five-year deposit matures every year, and every rung earns a five-year rate.
What the ladder costs in the first few years
Laddering is not free. Short-tenure deposits usually pay less than long-tenure ones, so a ladder earns less than a single five-year deposit in its early years. That gap is the price of liquidity and reinvestment flexibility.
GoPocket calculation using an illustrative rate card of 6.5% for one year, 6.75% for two, 7% for three, 7.1% for four and 7.25% for five years:
- The blended rate on the ladder in year one is the simple average of the five rates, about 6.92%. Method: (6.5 + 6.75 + 7 + 7.1 + 7.25) divided by 5.
- A single five-year deposit of Rs 5 lakh at 7.25% would earn about Rs 1,625 more in the first year. Method: (7.25% minus 6.92%) of Rs 5,00,000.
The rates used here are illustrative, not quotes from any bank. Actual rate cards differ by bank, by tenure bucket and by depositor category, and they change frequently. Run the same arithmetic with the rate card you are actually offered.
How the ladder behaves when rates move
- If rates rise: the rung maturing this year is reinvested at the higher rate, so the ladder catches up without any action beyond reinvesting. A single long deposit stays stuck at the old rate until maturity.
- If rates fall: the longer rungs continue earning the older, higher rate, which cushions the decline. A saver who had kept everything in one-year deposits would have to accept the new lower rate on the whole amount.
- If rates stay flat: the ladder converges on the five-year rate within five years, with the shortfall confined to the early years.
As of November 2026, the policy repo rate is 5.50%, raised by 25 basis points on 7 October 2026, with the stance changed to calibrated tightening. The next Monetary Policy Committee meeting runs from 2 to 4 December 2026, with the decision due on 4 December. Deposit rates do not move automatically with the repo rate, and each bank revises its card at its own pace.
Practical points when setting up a ladder
- Deposit insurance: DICGC cover applies up to the prescribed limit per depositor per bank, counting principal and interest together. Spreading rungs across more than one bank keeps a larger total inside cover.
- Avoid auto-renewal on autopilot: if the bank renews a matured deposit for the same original tenure, the ladder structure breaks. Set the renewal instruction to the tenure the ladder needs.
- Watch the TDS threshold: interest is aggregated per bank per financial year. Several rungs at one bank can cross the threshold sooner than expected, which triggers TDS at 10%.
- Cumulative or payout: cumulative deposits reinvest the interest, which suits a ladder being built up. A payout option suits someone who needs regular income from the rungs.
- Keep the rungs in round amounts: equal rungs make the reinvestment decision mechanical, which is the point of the method.
What laddering does not do
A ladder does not raise the return on a deposit. It manages reinvestment risk and liquidity, nothing more. It also does not protect against inflation: if the post-tax return on each rung is below the inflation rate, a ladder of deposits still loses purchasing power. And breaking a rung early still attracts the bank's premature withdrawal penalty on that deposit.
This article describes a method. GoPocket is a stockbroker and not a research analyst, and nothing here recommends a particular bank, tenure or product.
Sources
- Reserve Bank of India press releases - monetary policy decisions and MPC calendar
- Deposit Insurance and Credit Guarantee Corporation - scope of deposit insurance cover
- MPC meeting calendar 2026-27 - repo rate at 5.50% since 7 October 2026 and the 2 to 4 December 2026 meeting
This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Views attributed to third parties are those of the respective analysts and not of GoPocket. Investments in securities markets are subject to market risks; read all related documents carefully before investing.
GoPocket Invest Tech Private Limited - SEBI Reg. No. INZ000049235 | ARN: 136818